What are sweetened beverages, and which fall under the purview of excise tax?
Article
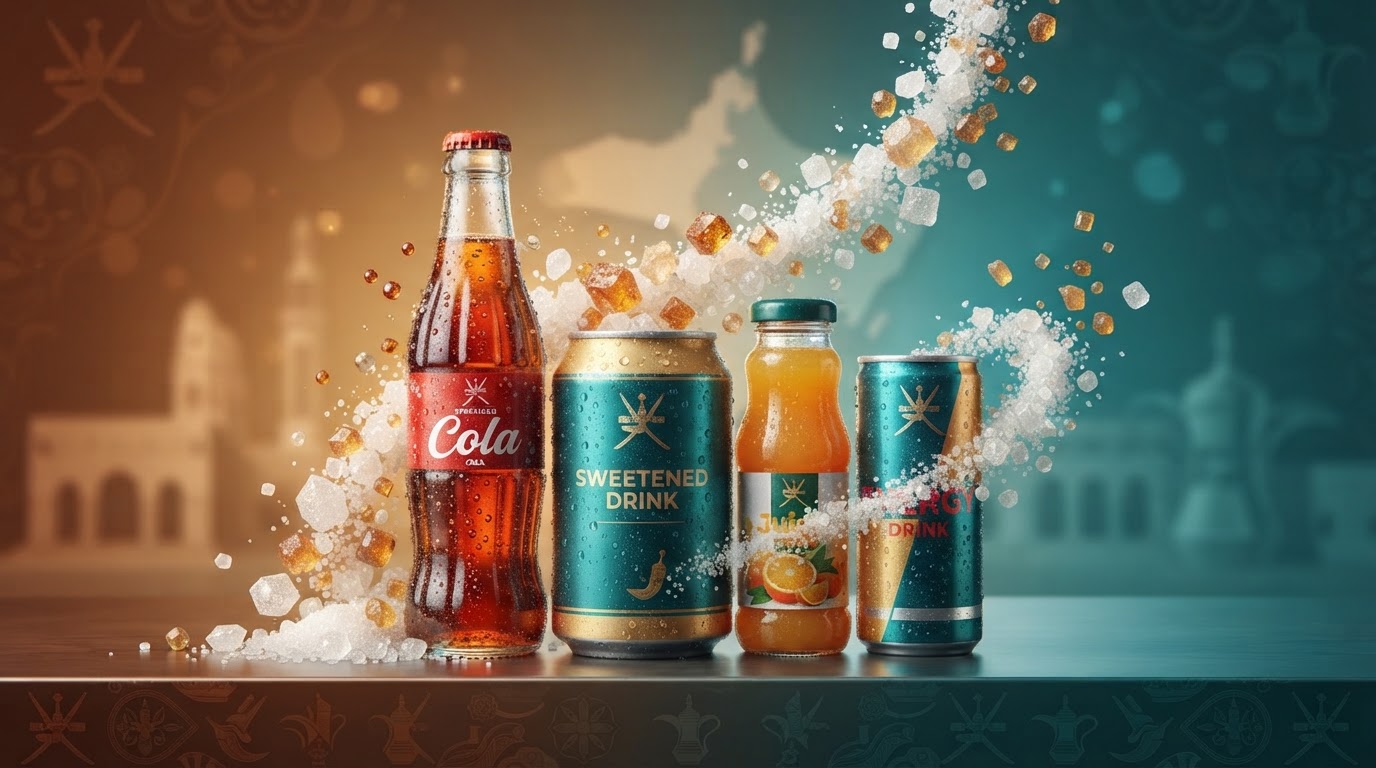
Sweetened beverages are drinks that contain added sugar, its derivatives, or alternative sweeteners — including concentrates, powders, or preparations used to make sweetened drinks. These beverages fall under the purview of Excise Tax in Oman, making it essential for beverage manufacturers, importers, and distributors to understand how their products are classified.
Added sugars classified as taxable include: Sucrose, Glucose, Fructose, Lactose, Galactose, Coco sugar, and Sugar cane. In addition, sugar substitutes are also treated as added sugars for excise tax purposes — including Stevia, Sucralose, Saccharin, Aspartame, Neotame, Acesulfame K, and Erythritol.
This means that even beverages marketed as "sugar-free" or "diet" may fall within the scope of excise tax if they use any of these substitutes. Correct product classification, pricing, labeling, and tax liability determination all depend on understanding which ingredients trigger the tax.
We at Leaderly can assist you with ensuring correct excise tax classification and full compliance for your products.
#SweetenedBeverages #AddedSugars #SugarSubstitutes #ExciseTax #TaxRegulations
Disclaimer: Leaderly blog posts are informational articles written by different authors from the broader Leaderly team. They do not constitute consultancy or professional advice and are not a substitute for tailored guidance. For advice specific to your circumstances, please contact us to arrange a formal engagement.